Author: admin

  • How Long Does Car Repo Stay on Your Credit: Uncover Truths

    When you first find out that your car has been repossessed, a flood of emotions and questions can overwhelm you. One pressing concern that might be circling in your mind is, “How long does this black mark stay on my credit report?”

    You’re not alone in wondering about the impact of a car repossession on your financial future. The thought of it haunting your credit score for years can be daunting. But understanding the timeline and consequences is the first step in regaining control and moving towards financial recovery.

    This article unpacks the details, offering you clarity and actionable insights to better manage and eventually improve your credit health. Dive in to discover how you can navigate this challenging situation with confidence and peace of mind.

    Impact Of Car Repossession On Credit Report

    Car repossession can significantly affect your credit report. This event signals lenders that you’re at risk. It shows you failed to meet loan obligations. The impact can linger for years, influencing your ability to borrow. Understanding this can help you manage future financial decisions.

    How Long Does Car Repossession Stay On Your Credit Report?

    Typically, a car repossession remains on your credit report for seven years. This duration starts from the date of your first missed payment. During this period, it can lower your credit score significantly. Lenders might see you as a high-risk borrower.

    Short-term Effects On Credit Score

    The immediate impact is a drop in your credit score. It might fall by 100 points or more. This makes it harder to obtain new credit or loans. The repossession appears as a negative mark on your report.

    Long-term Financial Consequences

    Over time, repossession affects your ability to secure favorable loan terms. Interest rates on future loans could be higher. It may limit access to credit cards with good benefits. This can hinder your financial growth.

    Potential Legal Issues

    Repossession might lead to legal complications. If your lender sells the car for less than what you owe, you may face a deficiency balance. This unpaid balance can result in a lawsuit or wage garnishment. Handling these issues can be stressful.

    Steps To Mitigate Impact

    • Review your credit report regularly.
    • Dispute any inaccuracies immediately.
    • Work on improving your credit score.
    • Pay bills on time to prevent future issues.

    Taking proactive steps can help lessen the impact. A focus on credit repair can improve your financial health over time.

    Duration Of Repossession On Credit Report

    Car repossession remains on a credit report for seven years from the date of the first missed payment. This negative mark can impact credit scores, making future loans or credit approvals more challenging. Understanding this timeline can help in planning credit repair strategies.

    Understanding how long a car repossession remains on your credit report is crucial for anyone trying to rebuild their financial life. A repossession can significantly impact your credit score, often leaving a lasting impression that may hinder future credit opportunities. But does it stay there forever? Not quite. Knowing the duration can help you plan your next steps more effectively.

    Impact Duration On Credit Report

    A car repossession typically stays on your credit report for seven years. This is a standard duration for most negative credit entries. Think of it like a stain that gradually fades but requires time and effort to fully disappear. During these seven years, the repossession will impact your credit score, but its effect diminishes over time.

    Effects Over Time

    Initially, your credit score might take a significant hit. The first couple of years are often the toughest, as lenders will see this as a red flag. However, as time progresses, the impact lessens. Are you wondering if there’s anything you can do during this period? Absolutely, you can focus on other positive credit behaviors to mitigate the damage.

    Strategies For Improvement

    Consider this: If you make consistent, on-time payments on other loans or credit cards, you can start to rebuild your credit profile. This proactive approach not only helps improve your score but also shows future lenders your commitment to financial responsibility. Have you thought about setting up automatic payments to ensure you’re always on time?

    Personal Experience Insight

    I remember a friend who faced a similar situation. She took steps to improve her credit by paying down debts and avoiding new loans. Over time, her credit score improved, and she was able to secure a mortgage despite the repossession still lingering on her report. Her experience underscores the importance of perseverance and strategic planning.

    Looking Forward

    What does your financial future look like? While seven years might seem daunting, remember that every small positive action counts. Start building good habits today, and you’ll find that the repossession’s impact on your credit report will gradually diminish.

    Factors Influencing Repossession Impact

    When a car is repossessed, it can have a significant impact on your credit report. However, the extent of this impact isn’t the same for everyone. Various factors can influence how long and how severely a repossession affects your credit score. Understanding these factors can help you better manage your credit health and prepare for the future.

    Type Of Loan

    Did you know the type of loan you have can affect the impact of a repossession? If you financed your car through a secured loan, the lender has more rights to take back the vehicle, which can lead to a quicker repossession process. On the other hand, an unsecured loan might give you more time to catch up on payments, potentially reducing the negative impact on your credit score.

    Consider this: a secured loan typically leaves a more significant mark on your credit report because it involves a tangible asset. Reflect on your own loan type and how it aligns with your financial strategies.

    Amount Owed

    The amount you owe at the time of repossession plays a crucial role. A higher balance can result in a greater negative impact on your credit score. This is because it indicates a larger financial obligation you were unable to meet.

    Imagine owing a substantial amount and missing payments. Your credit report will reflect this as a more severe financial misstep, affecting your creditworthiness for future loans. Ask yourself: how can you better manage your finances to avoid this scenario?

    Lender’s Reporting Practices

    Each lender has different reporting practices, which can influence how long a repossession stays on your credit report. Some lenders report repossessions immediately, while others might delay, giving you a chance to rectify the situation.

    Understanding your lender’s practices can give you a strategic advantage. If you’re aware of a potential delay, you might have time to negotiate or make arrangements to lessen the impact. Have you ever considered discussing reporting practices with your lender before signing a loan agreement?

    By knowing these factors, you can take proactive steps to protect your credit score. Whether it’s choosing the right type of loan, managing your debt wisely, or understanding lender practices, being informed puts you in control. What actions will you take to safeguard your credit health?
    How Long Does Car Repo Stay on Your Credit: Uncover Truths

    Credit: www.spyne.ai

    Credit Score Implications

    Car repossession can impact your credit score for up to seven years. This negative mark makes future loans harder to obtain. Regular payments and financial management can mitigate its effects over time.

    Credit Score Implications Understanding how a car repossession affects your credit score is essential to navigating your financial future. A repossession can significantly impact your credit report, often serving as a red flag to potential lenders. It’s a roadblock, but with the right knowledge, you can steer your way to recovery.

    Short-term Effects

    A car repossession typically stays on your credit report for up to seven years. Initially, you might notice a sharp drop in your credit score, sometimes by as much as 100 points or more. This immediate impact can make it difficult to secure new loans or credit cards. Lenders view a repossession as a sign of financial instability. It’s crucial to be aware that late payments leading up to the repossession also contribute to credit damage. Each missed payment adds another blemish to your report, compounding the negative effects.

    Long-term Effects

    While the initial impact is severe, the effects of a repossession can fade over time. As years pass, the weight of the repossession on your credit score diminishes. This gradual recovery depends on your efforts to rebuild your credit. Engaging in positive credit behaviors like paying bills on time and reducing debt can accelerate your recovery. You might find that after a few years, the repossession’s influence lessens, allowing you to access better credit opportunities. Are you prepared to take the steps necessary to improve your credit health? By understanding these implications, you can actively work towards a stronger financial future. Remember, it’s not just about the past, but how you manage your credit moving forward.

    Removing Repossession From Credit Report

    Removing a car repossession from your credit report can be challenging. This negative mark can impact your credit score for years. But, there are ways to address it. Understanding these options can help you move forward.

    Negotiating With Lender

    Start by contacting your lender. Discuss your situation openly. They may agree to remove the repossession in exchange for payment. This is called a “pay for delete” agreement. Make sure to get any agreement in writing. This ensures clarity and future protection.

    Disputing Errors

    Check your credit report for errors. Mistakes can happen. If you find inaccuracies, dispute them with the credit bureau. Provide evidence to support your claim. This can lead to the removal of the repossession. Regularly monitoring your credit report helps catch errors early.

    Hiring Credit Repair Services

    Consider hiring credit repair services. These professionals understand credit laws. They can negotiate or dispute on your behalf. This approach can save you time and stress. Always research before choosing a service. Look for reputable companies with good reviews.

    Strategies To Rebuild Credit

    Understanding how long a car repo stays on your credit is vital. Typically, repossessions remain for seven years. To rebuild credit, focus on timely payments and reducing debt. Consider working with a credit counselor to navigate complex situations.

    Rebuilding your credit after a car repossession can seem daunting, but it’s entirely possible with the right strategies. While a repo can linger on your credit report for up to seven years, taking proactive steps can help mitigate its impact and improve your score over time. Let’s explore some effective ways to get your credit back on track.

    Timely Bill Payments

    Paying bills on time is the cornerstone of good credit management. Every timely payment you make can positively affect your credit score. Set reminders or automate payments to avoid missing due dates. Even small bills like utilities or phone payments contribute to your credit history. Prioritize payments that report to credit bureaus, as these will have the most direct impact on your score.

    Secured Credit Cards

    Secured credit cards can be a powerful tool in rebuilding your credit. These cards require a deposit that serves as your credit limit, minimizing risk for the lender. Use this card responsibly by keeping your balance low and paying it off each month. This demonstrates your ability to manage credit effectively. Consider starting with a card that offers a gradual increase in credit limits, rewarding your responsible usage.

    Credit Counseling

    If you’re feeling overwhelmed, credit counseling can offer valuable guidance. Professional counselors can help you understand your financial situation and create a personalized plan. They can assist in negotiating with creditors and provide tips on managing your finances better. Ask yourself, could an expert’s perspective be the key to your credit recovery? Seeking help might be the turning point you need. By integrating these strategies into your financial routine, you can steadily rebuild your credit profile, turning challenges into opportunities for growth.

    Legal Rights And Consumer Protections

    Understanding your legal rights and consumer protections is crucial when dealing with a car repossession on your credit report. The aftermath of a repossession can seem overwhelming, but knowing the laws designed to protect you can help you navigate this challenging situation more effectively. Whether you’re facing a recent repo or trying to clean up your credit, these insights will empower you to take control of your financial health.

    Fair Credit Reporting Act

    The Fair Credit Reporting Act (FCRA) is a federal law that governs how your credit information is collected and shared. Under the FCRA, you have the right to dispute inaccurate information on your credit report. If you believe your repossession was reported incorrectly, you can challenge it.

    Think about how many errors could be lurking in your report—errors you have the power to correct. By taking action, you can potentially reduce the negative impact of a repossession on your credit score. The FCRA also mandates that repossessions, like other negative items, must eventually be removed from your credit report, typically after seven years.

    State-specific Laws

    Your state may have additional laws that offer further protection. These laws can differ significantly, impacting how repossession is handled and reported. Some states require lenders to notify you of their intent to repossess, giving you a chance to rectify the situation before it affects your credit.

    Have you checked your state laws? They might offer you more leverage than you realize. By understanding these state-specific protections, you can make informed decisions and potentially mitigate the impact on your credit. Researching and utilizing these laws can be a game-changer in your credit repair journey.

    How Long Does Car Repo Stay on Your Credit: Uncover Truths

    Credit: www.wmtxlaw.com

    How Long Does Car Repo Stay on Your Credit: Uncover Truths

    Credit: asapcreditrepairusa.com

    Frequently Asked Questions

    Does A Car Repo Ever Go Away?

    A car repossession typically remains on your credit report for seven years. It can negatively impact your credit score. You may negotiate with the lender to have it removed after paying off the debt. Consistent, timely payments can help improve your credit score over time.

    Can A Repossession Be Removed From A Credit Report?

    Yes, a repossession can be removed from a credit report. Dispute inaccuracies with credit bureaus. Negotiate with lenders for removal upon payment. Use credit repair services for assistance. Removal improves credit score and financial opportunities. Always ensure accurate information on your report.

    How Long Until A Repo Is Off Your Record?

    A repossession typically stays on your credit report for seven years. This period begins from the date of the first missed payment that led to the repossession. Regular credit monitoring can help you stay informed. Rebuilding credit during this time is crucial for improving your financial standing.

    How Bad Is A Car Repossession On Your Credit?

    A car repossession significantly impacts your credit score, dropping it by up to 100 points. It stays on your credit report for seven years, making it harder to secure loans or favorable interest rates. Recovering from repossession requires consistent, responsible credit behavior over time.

    Conclusion

    A car repo affects your credit for seven years. This can impact loan approvals and interest rates. It’s crucial to rebuild your credit actively. Paying bills on time helps. Keep credit card balances low. Consider a secured credit card. Monitor your credit report regularly.

    Dispute errors promptly if found. Patience is key during this period. Positive actions improve your score over time. Remember, small steps lead to big changes. Focus on financial habits that strengthen your credit. With effort, your score will rise again.

    Stay committed to maintaining good credit health.

  • How Many Missed Car Payments before Repo: Avoid Repossession

    You’ve just received a letter from your car loan company, and suddenly your heart skips a beat. Are you worried about missing a car payment?

    You’re not alone. Many people find themselves in this nerve-wracking situation. You might be asking yourself, “How many missed car payments before repo? ” This question is crucial, and understanding the answer can save you from losing your vehicle. Imagine the relief of knowing exactly how close you are to repossession and having a strategy to avoid it.

    This article will guide you through the process, helping you navigate the terms of your loan agreement and explaining what lenders typically do when payments are missed. You’ll also discover practical steps to take if you’re behind on payments. Before you panic, let’s dive into what really happens when you fall behind on your car payments and how you can keep your wheels firmly under your control.

    Car Loan Basics

    Understanding the basics of car loans is crucial, especially when considering how missed payments can impact your financial stability. You might have asked yourself how many missed car payments before your vehicle is at risk of repossession. The answer lies in the details of your car loan agreement. By familiarizing yourself with the loan terms and conditions, and recognizing the importance of timely payments, you can better manage your financial obligations and avoid the stress of a repossession.

    Loan Terms And Conditions

    Every car loan comes with specific terms and conditions that outline your repayment responsibilities. These terms specify the monthly payment amount, interest rates, and due dates. Pay close attention to any clauses related to missed payments, as they define the grace period before your lender can take action.

    Do you know how many payments you can miss before your car is repossessed? While some lenders allow a short grace period, others might initiate repossession after just one missed payment. It’s crucial to read these terms thoroughly to avoid surprises.

    • Review the penalty fees for late payments.
    • Understand the lender’s repossession policy.
    • Check for any provisions for payment extensions or adjustments.

    Importance Of Timely Payments

    Timely payments are not just about keeping your car; they reflect your financial discipline. Consistent payments build trust with your lender, potentially opening doors to better credit opportunities in the future. Missing payments can damage your credit score, making future loans more expensive or difficult to obtain.

    Have you ever considered the long-term impact of missed payments? A single late payment can lead to increased interest rates, additional fees, and even repossession. It’s a domino effect that can spiral out of control if not addressed promptly.

    Consider setting reminders or automating your payments to ensure they are always on time. Prioritize your car loan as part of your monthly budget to avoid financial pitfalls.

    How Many Missed Car Payments before Repo: Avoid Repossession

    Credit: www.instagram.com

    Repo Triggers

    Understanding repo triggers is crucial for car owners. Missing payments can lead to repossession. Knowing what sets off this process helps you avoid it.

    Missed Payment Threshold

    Car lenders have different rules. Most start repossession after two or three missed payments. Some may act faster. It’s vital to check your contract. Knowing your lender’s policy can help you plan better.

    State Laws And Regulations

    State laws impact repossession. They set the rules lenders must follow. Some states require a notice before repossession. Others allow instant action after a missed payment. Understanding your state’s laws is key. It protects your rights as a borrower.

    Consequences Of Repossession

    Missing two or three car payments might lead to repossession. Each lender has different rules. It’s important to check your loan agreement to understand the specific terms. Repossession can harm your credit score and make it hard to get loans in the future.

    Repossession of a car comes with several serious consequences. It’s not just losing access to a vehicle. It affects your financial health and stability.

    Impact On Credit Score

    Repossession leaves a negative mark on your credit report. Lenders view this as a sign of financial distress. It can lower your credit score by many points. This makes it harder to get loans in the future. Higher interest rates on loans become more likely. This negative mark stays on your report for seven years.

    Financial Repercussions

    Repossession often leads to more financial burdens. You might owe a deficiency balance. This happens if the car sells for less than your loan balance. Lenders might sue you for this remaining amount. Legal fees and collection costs add to your financial woes. You’ll also need to find alternative transportation. This adds unexpected costs to your budget.
    How Many Missed Car Payments before Repo: Avoid Repossession

    Credit: www.wmtxlaw.com

    Signs Of Financial Trouble

    Missing car payments can lead to serious financial trouble. Usually, missing three payments could trigger repossession. It’s crucial to communicate with lenders early to find solutions.

    Understanding the signs of financial trouble is crucial for avoiding the stress of missed car payments and potential repossession. Recognizing these signs early can empower you to take action before things spiral out of control. Have you ever wondered if your financial habits might be leading you toward trouble?

    Warning Signs

    – Constantly Overdue Bills: If your bills are consistently piling up and you’re playing catch-up every month, it’s a clear sign something is amiss. Missing deadlines occasionally might happen to anyone, but frequent delays are a red flag. – Dipping into Savings: Are you regularly using your savings to cover daily expenses? This indicates your income might not be sufficient to cover your lifestyle. Savings should ideally be for emergencies or future plans, not daily survival. – Increased Credit Card Debt: Relying on credit cards for essentials like groceries and utilities can quickly lead to overwhelming debt. If you find your credit card balance increasing each month, it’s time to reassess your budget.

    Common Causes Of Missed Payments

    – Unexpected Expenses: Life is full of surprises, and sometimes those surprises come with a hefty price tag. Medical bills, car repairs, or family emergencies can all stretch your budget thin. – Job Loss or Reduced Income: A sudden change in employment status can dramatically affect your ability to meet financial commitments. If you’ve recently lost your job or faced a pay cut, it’s essential to adjust your spending immediately. – Poor Budgeting Skills: Without a clear plan for your money, it’s easy to overspend. Do you track your expenses and know exactly where your money goes each month? If not, creating a budget can be a game-changer. By identifying these warning signs and understanding their causes, you can take proactive steps to protect your financial well-being. How will you address these issues before they lead to missed payments and potential repossession?

    Communication With Lenders

    Communication with your lender is essential if you’re facing the possibility of missed car payments. By maintaining an open line of communication, you can often find solutions that prevent repossession. The key is to be proactive and honest about your situation.

    Proactive Contact

    Don’t wait for your lender to reach out to you. As soon as you realize you might miss a payment, give them a call. It shows responsibility and can set the tone for a cooperative relationship.

    A friend of mine was in this exact situation. Instead of avoiding the issue, she contacted her lender and explained her temporary financial struggles. This led to a more understanding approach from the lender’s side, allowing her to find a solution without the stress of looming repossession.

    Negotiating Payment Plans

    Once you’ve initiated contact, discuss the possibility of adjusting your payment plan. Lenders often have options like extending the loan term or temporarily reducing payments.

    Consider asking about any hardship programs they might offer. These programs can provide temporary relief and help you stay on track without damaging your credit.

    What would you do if your lender offers a solution you hadn’t considered? It’s important to stay open-minded and flexible during these discussions. Negotiating isn’t just about what you want, but finding a mutually beneficial arrangement.

    Remember, taking the initiative and communicating effectively with your lender can be the difference between keeping your car and facing repossession. So, how will you approach the conversation?

    Preventive Measures

    Preventive measures can help avoid car repossession after missed payments. Contact lenders early to discuss payment options. A proactive approach can protect your credit score.

    Preventing car repossession starts with proactive planning. This involves managing finances wisely and preparing for unexpected situations. Understanding these preventive measures can help maintain stability and avoid missed payments.

    Budgeting Strategies

    Creating a budget is crucial. Start by listing all monthly expenses and income. Allocate funds for essential bills like rent and utilities. Set aside a specific amount for car payments. This reduces the risk of missing a payment. Use budgeting apps for easy tracking. They provide visual insights into spending habits. Adjust your budget as income or expenses change. Regular reviews help maintain balance.

    Emergency Funds

    An emergency fund acts as a safety net. It covers unexpected expenses like medical bills or car repairs. Aim to save at least three months of living expenses. Start small if needed, and gradually increase savings. Deposit a fixed amount regularly into a separate account. This ensures funds are available when needed. Emergency funds prevent financial strain during tough times. They can cover a missed payment if necessary.

    Repossession Alternatives

    Missing a car payment can lead to repossession after two or three consecutive missed payments. Consider alternatives to avoid losing your vehicle, such as refinancing, negotiating payment plans, or seeking temporary financial assistance.

    Facing the possibility of car repossession can be daunting, but it’s crucial to remember that there are alternatives available that might help you keep your vehicle. By exploring these options, you can potentially avoid the stress and financial setbacks associated with repossession. Whether it’s through refinancing your loan or considering voluntary repossession, each alternative offers a unique approach to handling your missed car payments responsibly.

    Loan Refinancing

    Refinancing your car loan can be a game-changer. This option allows you to adjust your loan terms, potentially reducing your monthly payments to fit your current financial situation. Imagine having a little extra cash each month; it could make all the difference. You might wonder, how does refinancing work? Essentially, you get a new loan to pay off your existing one, often with a lower interest rate or extended term. This could be the lifeline you need to avoid repossession. Remember, refinancing isn’t just for homeowners. Many lenders offer car refinancing options, so don’t hesitate to ask your lender about it. It might surprise you how accommodating they can be.

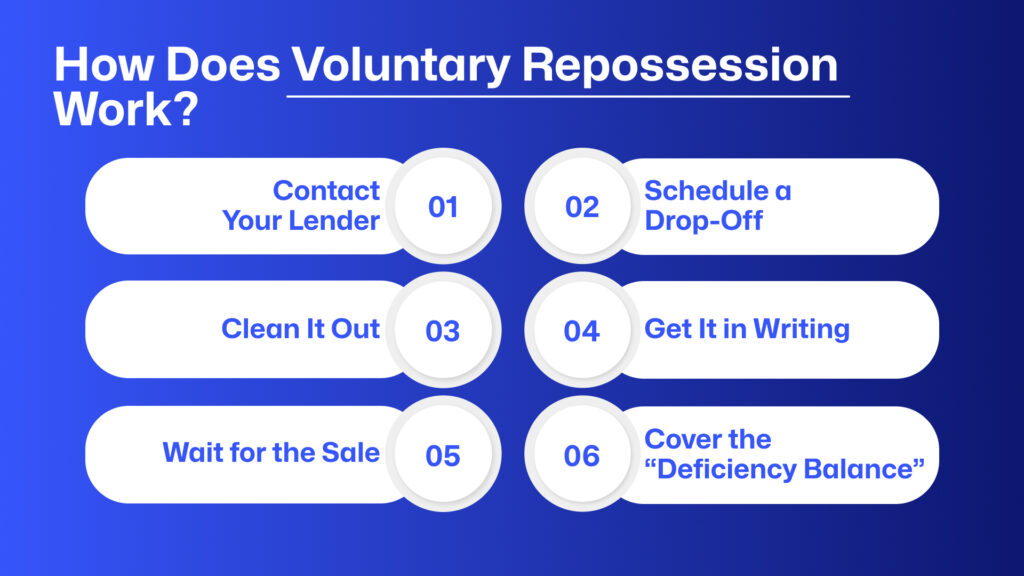
    Voluntary Repossession

    Voluntary repossession is another alternative worth considering, especially if keeping the car isn’t feasible. By surrendering your vehicle willingly, you might mitigate some of the negative impacts on your credit score compared to a forced repossession. Why choose this route? Sometimes, freeing yourself from an unmanageable debt burden can pave the way for financial recovery. It gives you control over the situation, allowing you to plan your next steps without the stress of a surprise repo. Discuss your options with your lender. They might offer a more favorable settlement or payment plan upon voluntary repossession. It’s about taking proactive steps and making informed decisions that align with your financial goals.
    How Many Missed Car Payments before Repo: Avoid Repossession

    Credit: www.nerdwallet.com

    Legal Rights And Resources

    Missed car payments can lead to repossession. Typically, after two or three missed payments, lenders may start the repossession process. It’s crucial to understand your rights and seek resources to potentially prevent repossession.

    Understanding the legal rights and resources available to you when facing potential car repossession can be a game-changer. Many people don’t realize they have options before their vehicle is taken away. Knowing your rights and where to seek help can prevent a stressful situation from escalating.

    Understanding Consumer Rights

    Before a lender can legally repossess your car, they must adhere to specific laws. These laws vary by state, but there are general guidelines you can expect. Most lenders are required to notify you before repossession, giving you a chance to catch up on payments. You have the right to retrieve any personal belongings from your vehicle after it’s repossessed. It’s essential to know this so you can act swiftly. Also, once your car is repossessed, lenders must inform you about how to reclaim it. This often involves paying off the loan in full, but understanding this process can provide a clearer path forward.

    Seeking Professional Help

    Sometimes, navigating the complexities of repossession can feel overwhelming. This is where professional help comes in. Consider consulting with a consumer rights attorney. They can provide tailored advice based on your situation and help protect your rights. Credit counseling services are also a valuable resource. They can offer financial advice and possibly negotiate with your lender to create a manageable payment plan. Have you thought about reaching out to a local non-profit organization? Many offer free or low-cost legal advice and can guide you through the process. By understanding your rights and seeking help, you can turn a challenging situation into an opportunity for financial stability.

    Frequently Asked Questions

    How Long After A Missed Car Payment Before Repossession?

    Repossession can occur after a single missed payment, but typically happens after 60 to 90 days. Policies vary by lender, so it’s crucial to communicate and negotiate payment arrangements to prevent repossession. Contact your lender immediately if facing financial difficulties to explore options.

    How Many Missed Payments Before Car Repossession?

    Generally, lenders initiate repossession after three missed payments. However, this can vary based on lender policies. It’s crucial to communicate with your lender if you’re facing difficulties. Some lenders may offer grace periods or alternative payment plans. Always review your loan agreement to understand specific terms and conditions.

    Can One Missed Payment Lead To Repossession?

    Typically, one missed payment doesn’t lead to immediate repossession. Lenders usually allow a grace period. However, consistent communication with your lender is key. They may offer solutions like a payment extension. Ignoring notices can increase the risk of repossession. Always address missed payments promptly to avoid complications.

    What Are The Consequences Of Missed Car Payments?

    Missed car payments can damage your credit score significantly. They may also lead to late fees and increased interest rates. Prolonged non-payment can result in vehicle repossession. This can further affect your credit and financial stability. It’s essential to address any missed payments as soon as possible.

    Conclusion

    Missing car payments can lead to repossession. Avoid this situation by managing your finances. Stay informed about your loan terms. Communicate with your lender if you’re struggling. They might offer solutions. This helps prevent repossession. Always prioritize your car payment.

    It’s crucial for your financial stability. A missed payment can impact your credit score. Protect your credit by paying on time. Understanding your loan agreement is key. Know your rights and obligations. Being proactive can save your car. Remember, a little planning goes a long way.

    Stay ahead and keep your car safe.

  • Car Repair Payment Plan: Affordable Solutions for All

    Imagine this: your car suddenly breaks down, leaving you stranded and stressed. You know it needs repairs, but you’re worried about the hefty bill that comes with it.

    That’s where a car repair payment plan comes in. These plans can ease the financial burden and get your car back on the road without emptying your wallet. We’ll dive into how these plans work, their benefits, and how you can find the right one for you.

    Stick around to discover how you can drive away from repair stress and stay financially secure.

    Car Repair Payment Plan: Affordable Solutions for All

    Credit: www.facebook.com

    Benefits Of Payment Plans

    Car repair payment plans offer flexibility, easing the burden of unexpected expenses. They allow you to spread costs over time, ensuring your vehicle gets necessary repairs without financial strain. This approach helps maintain your car’s performance without compromising your budget.

    When your car breaks down, the last thing you need is the financial strain of an unexpected repair bill. Car repair payment plans can alleviate this stress, providing a practical solution that allows you to spread the cost over time. But what exactly makes these plans beneficial?

    Flexible Financial Options

    Payment plans offer you the flexibility to manage your finances without being hit by a large lump sum. Instead of paying all at once, you can tailor payments to fit your budget. This flexibility allows you to focus on getting your car back on the road rather than stressing over finances.

    Immediate Repair Access

    Imagine having your car repaired immediately without waiting to save up the full amount. Payment plans ensure you don’t have to delay necessary repairs. This means you can maintain your daily routine without disruption, whether that’s getting to work, school, or other important commitments.

    Improved Financial Planning

    With a structured payment plan, you can better predict your monthly expenses. This predictability helps you plan your budget more effectively, avoiding unforeseen financial pressure. A clear schedule of payments aids in maintaining control over your finances, reducing the risk of debt.

    Building Credit Score

    Did you know that timely payments on a repair plan can positively impact your credit score? Regular, on-time payments demonstrate financial responsibility, which can enhance your credit profile. This can be an unexpected benefit that supports your financial health in the long run.

    Peace Of Mind

    The peace of mind that comes with knowing you have a financial plan is invaluable. Payment plans give you the assurance that you can manage repair costs without sacrificing other necessities. This peace of mind can be a significant relief during stressful times. Wouldn’t you agree that minimizing financial stress can make dealing with car repairs significantly easier? Payment plans can be a crucial part of that process, offering numerous benefits that extend beyond just the repair itself.

    Types Of Payment Plans

    Car repair payment plans offer flexible options like installment payments, interest-free periods, or financing through service providers. These plans help manage repair costs without immediate financial strain, providing peace of mind and ensuring vehicle upkeep.

    When managing car repair expenses, having flexible payment plans helps. These plans offer a manageable way to pay for necessary services. Understanding the types of payment plans can guide you to a suitable option for your budget.

    Interest-free Options

    Interest-free options let you pay over time without extra costs. Usually, these plans divide the total amount into equal installments. No interest means you pay only for the service. Many repair shops partner with financial institutions to offer these plans. It’s a straightforward way to spread payments without financial stress.

    Flexible Monthly Payments

    Flexible monthly payments adapt to your financial situation. These plans offer varied terms to suit different needs. You can choose a payment schedule that aligns with your income. This flexibility ensures you can maintain other financial commitments. Repair shops may offer in-house financing for this purpose. Always check the terms to understand any potential fees.

    Deferred Payment Agreements

    Deferred payment agreements allow you to delay payments. This option is helpful if you face immediate financial constraints. You can postpone the start of your payments for a set period. It provides breathing room to arrange your finances. This plan may include interest after the deferred period. Always review the terms to avoid unexpected charges.

    Selecting The Right Plan

    Choosing the best car repair payment plan ensures manageable costs and peace of mind. Consider your budget and repayment terms carefully. Compare various plans to find one that fits your needs.

    Selecting the right car repair payment plan can feel overwhelming. There are many options available. Choosing the right one is crucial for your financial peace. Each plan offers different features and terms. Knowing how to evaluate these can save you money and stress. Let’s explore some key steps to help you decide.

    Assessing Your Financial Situation

    Begin by evaluating your current financial status. This step will guide your decision. Determine how much you can afford monthly for car repairs. Review your income and expenses. This helps identify a realistic payment range. Avoid straining your budget with higher payments. Consider any upcoming expenses that might impact your finances.

    Comparing Plan Features

    Not all payment plans are the same. Look at the features each plan offers. Some plans provide flexible payment options. Others might include additional services like free towing. Check for any hidden fees or penalties. This could affect your overall cost. List the features that are most important to you. This will help narrow down your choices.

    Evaluating Long-term Costs

    Consider the long-term costs associated with each plan. A plan with low monthly payments might have higher interest rates. Calculate the total cost over the plan’s duration. This helps you understand the true financial impact. Look for plans with the best balance of cost and benefits. This ensures you make a wise investment in your car’s upkeep.
    Car Repair Payment Plan: Affordable Solutions for All

    Credit: icash.ca

    Working With Repair Shops

    Car repair payment plans offer flexibility for unexpected expenses. Customers can spread costs over time, easing financial strain. This approach helps maintain vehicle health without immediate financial burden.

    When your car needs repairs, choosing the right shop is key. You want a place that offers a fair payment plan. This can make dealing with costs easier. Working with repair shops involves clear communication and understanding.

    Negotiating Terms

    Discuss payment plans early with the repair shop. Ask if they offer flexible options. Some shops may allow you to pay in installments. This can ease the financial burden. Be clear about your budget. This helps in finding a plan that suits your needs.

    Trusted Repair Providers

    Choose repair shops with a good reputation. Trusted providers are more likely to offer fair terms. Check online reviews and ask for recommendations. A reliable shop ensures quality service and transparent payment plans. Building a relationship with a trusted provider can also lead to better terms.

    Understanding Shop Policies

    Before agreeing to a payment plan, understand the shop’s policies. Know what happens if a payment is late. Some shops might charge extra fees. Clarifying these details prevents surprises later. Read the fine print or ask for it to be explained. Understanding policies helps you make informed decisions.

    Avoiding Common Pitfalls

    Understanding car repair payment plans can prevent financial stress. Choose a plan with clear terms and no hidden fees. Ensure the plan suits your budget to avoid future issues.

    When considering a car repair payment plan, it’s essential to navigate wisely to avoid common pitfalls. These plans can offer financial relief, allowing you to fix your car without breaking the bank immediately. However, without careful attention, they might lead you into unanticipated challenges. Understanding these pitfalls can empower you to make informed decisions and protect your financial health.

    Hidden Fees

    Hidden fees can catch you off guard. Before signing any agreement, scrutinize the terms and conditions thoroughly. Ask for a detailed breakdown of all costs involved. Are there processing fees or penalties for early payment? Sometimes, these charges are tucked away in the fine print, which can inflate your total expenses unexpectedly. Always ensure transparency and demand clarity from your service provider.

    Interest Rate Traps

    Interest rates are another critical factor to consider. While a payment plan might seem affordable initially, high-interest rates can quickly escalate costs. Compare rates from different providers and assess the total amount you’ll end up paying. A friend once shared how a low monthly payment turned into a financial burden due to steep interest rates. Avoid this trap by calculating the full cost over time and choosing the most reasonable option.

    Overextending Budgets

    It’s easy to fall into the trap of overextending your budget when opting for a payment plan. Make sure the monthly payments fit comfortably within your financial limits. Consider your other expenses and obligations; will the payment plan impact your ability to meet them? Balancing your budget is crucial. Reflect on what you can realistically afford and avoid stretching your finances too thin. Remember, a temporary fix shouldn’t compromise your long-term financial stability.
    Car Repair Payment Plan: Affordable Solutions for All

    Credit: lasalleautocentre.com

    Legal And Financial Considerations

    Understanding the legal and financial aspects of car repair payment plans can prevent unexpected costs. Ensure clear terms and conditions are in place. Reviewing interest rates and payment schedules helps manage expenses effectively.

    Navigating the world of car repair payment plans can be tricky, especially when considering the legal and financial aspects. Understanding the implications of these plans is crucial for making informed decisions and ensuring your rights are protected. Let’s dive into some key areas you should be mindful of before committing to a payment plan.

    Credit Score Impact

    Your credit score can be significantly affected by a car repair payment plan. Timely payments can boost your score, showcasing reliability and financial responsibility. But what happens if you miss a payment? This can lead to a negative mark, potentially lowering your score and affecting future credit opportunities. Consider how this plan fits into your overall financial picture. Is it worth the risk to your credit score?

    Contractual Obligations

    Signing up for a payment plan involves entering into a contract. This means you’re legally bound to fulfill the terms agreed upon. Carefully read through the contract’s fine print. Are there hidden fees or penalties for late payments? What are the terms if you want to pay off the debt early? Ensure you’re comfortable with all obligations before signing on the dotted line.

    Consumer Rights

    As a consumer, you have rights that protect you in financial agreements. Be aware of these rights, which can include the right to receive clear information about the plan terms and the ability to dispute discrepancies. If you feel your rights are being violated, don’t hesitate to seek advice or legal assistance. Have you ever felt trapped by a contract? Knowing your rights can empower you to navigate such situations effectively. Understanding these considerations can help you make a more informed decision about car repair payment plans. After all, your financial health is just as important as maintaining your vehicle.

    Success Stories

    Car repair payment plans help drivers manage repair costs without stress. Success stories highlight how these plans offer financial relief and keep cars running smoothly. Flexible payment options ensure affordability, making vehicle maintenance accessible for everyone.

    Success stories from car repair payment plans can inspire and guide others. These tales show how financial strategies help many manage repair costs. They highlight real-life experiences and demonstrate the effectiveness of payment plans.

    Overcoming Financial Hurdles

    Many face unexpected car repair costs. A payment plan helped Sarah, a single mom, fix her car without stress. She divided the expense into manageable monthly payments. This approach allowed her to maintain her budget and keep her car running.

    Maintaining Daily Life

    John’s story is about keeping life on track. His car broke down, impacting his commute. By using a payment plan, he quickly repaired his vehicle. He continued his daily routine without financial strain, demonstrating the plan’s practicality.

    Supporting Family Needs

    The Wilson family needed their car for school and work. A major repair threatened their routine. They opted for a payment plan, ensuring the car was fixed promptly. This choice supported their family needs, showing the importance of flexible payment options.

    Enabling Career Opportunities

    Emma’s car was essential for her new job. A breakdown could have hindered her career. She utilized a payment plan to cover repair costs. This decision allowed her to seize career opportunities and maintain mobility.

    Frequently Asked Questions

    Can I Pay In Installments For Car Repairs?

    Yes, many repair shops offer installment plans for car repairs. Check with your local mechanic for options. Payment terms may vary, so inquire about interest rates and fees. Flexible payment plans can ease financial strain. Always read the terms carefully before agreeing to any payment plan.

    Can I Use Afterpay For Car Repairs?

    Yes, AfterPay can be used for car repairs. Check with your repair shop if they accept AfterPay. It allows you to split payments into installments, making it easier to manage costs. Always confirm terms with the service provider.

    How To Pay For Auto Repairs When You Have No Money?

    Consider a payment plan with the repair shop. Explore credit cards, personal loans, or ask family for help. Research local charities or government programs for assistance.

    What Happens If You Can’t Afford To Pay A Mechanic?

    Negotiate a payment plan with the mechanic. Consider seeking financial assistance or community programs. DIY repairs could be an option. Explore bartering services if possible. Seek advice from friends or online forums.

    Conclusion

    Car repair payment plans offer valuable support. They ease financial stress. You can manage costs without upfront payment. These plans provide flexibility for your budget. Choose options that fit your needs. Ensure your vehicle stays in top shape. Repair costs don’t have to be overwhelming.

    Explore payment plans that work for you. Ask questions and understand the terms. Make informed decisions for your car repairs. Keep your vehicle running smoothly without breaking the bank. A little planning can go a long way. Make car care affordable and stress-free with the right payment plan.